Further reading
The Small Daily Trims That Fund a Big Goal
A used car, a down payment, a safer set of tires. Here is how packed lunches and secondhand clothes quietly add up to the thing you actually want.
There is a particular kind of tired that comes from wanting something expensive. A car that starts every morning. The down payment on a small house with a yard. A washing machine that does not need to be coaxed. The number sits out there, five figures wide, and every time you look at your checking account the gap seems to laugh at you.
The advice you usually get is to earn more, which is true and also not very useful this Tuesday. The other half of the answer is duller and completely within reach: find the money that is already leaving your life in ten-dollar pieces, and point it at the thing you actually want.
Start by turning the goal into a daily number
A big number is paralyzing. A daily number is a decision you can make.
Say you want six thousand dollars for a reliable used car in eighteen months. That is about three hundred and thirty-five dollars a month, or eleven dollars a day. Say you want twelve thousand dollars toward a down payment in three years. That is also about eleven dollars a day.
Eleven dollars is not a life change. It is a sandwich, a delivery fee, or two streaming services you forgot you had. Once you see the goal in daily money, the question stops being how do I find six thousand dollars and becomes where are my eleven dollars going right now.
Write the goal down with a date on it. "Twelve thousand by March 2029" survives a bad week. "Save more" does not.
Lunch is the largest single lever most people have
A bought lunch runs twelve to eighteen dollars once tax, tip, and the delivery surcharge have had their turn. Five of those is seventy-five dollars a week. Packing something decent — leftovers, a real sandwich, fruit, something you actually like — runs three or four dollars. The difference is roughly fifty dollars a week, or twenty-six hundred dollars a year.
That single habit funds nearly half of a used car by itself.
Two notes from people who have tried this and failed. First, do not go from five bought lunches to zero; go to one. The bought lunch on Friday stops the whole plan from feeling like punishment, and you keep four days of savings instead of quitting after three weeks with none. Second, pack it the night before. Willpower at 7:15 in the morning is a much weaker material than a container already sitting in the fridge.
Buy the same clothes, one season later
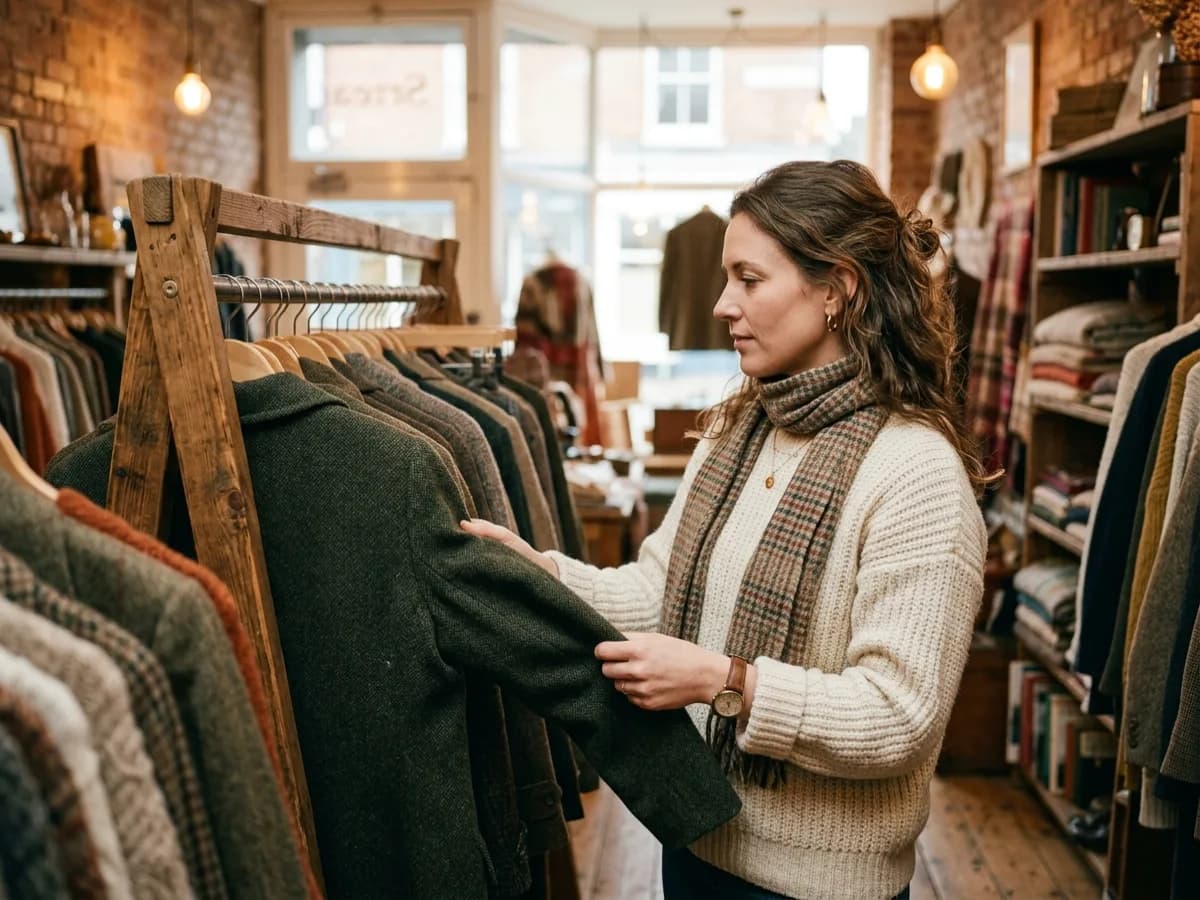
Secondhand clothing is the most underrated discount in American life. Thrift shops, consignment racks, and the resale apps are full of good coats, work shirts, and barely-worn kids' clothes at a quarter of the original price, often from the exact brands you would have bought new.
Children's clothing is the clearest case: a four-year-old outgrows a jacket in one winter, so the jacket is nearly new when it reaches the rack. Adults do best with the sturdy things — wool coats, denim, leather boots, work bags — where the used version is often better made than the new one at the same price.
A household that spends twelve hundred dollars a year on clothing and shifts half of it secondhand keeps four to five hundred dollars a year without anyone at work noticing a thing.
Cut the bills once instead of resisting them daily
Daily restraint is expensive to maintain. One afternoon of paperwork is not, and it usually pays more.
Go through the last two months of charges and read every line out loud. Cancel the subscriptions you cannot remember using. Call your phone company and ask what plan you would get as a new customer, then ask for it. Get two new quotes on your car insurance; loyalty is rarely rewarded there. Move your savings to an account that actually pays interest instead of one paying almost nothing.
Most people find forty to a hundred dollars a month in an hour of this, and unlike the packed lunch, they never have to decide about it again.
A few more that cost nothing but attention: a grocery list written against a plan for the week, the second delivery order replaced by the ten-minute walk to pick it up, the gym membership swapped for the one you would actually attend, and the eight-dollar coffee narrowed to the days you genuinely enjoy it rather than the days you are simply on autopilot.
Move the money the same day it appears
Here is the part that decides whether any of this works: trimmed money that stays in checking gets spent. Not deliberately — it just quietly refills the space it left.
Open a separate savings account, name it after the goal, and set an automatic transfer for the day after payday for the amount you trimmed. Start with the amount you are sure of, not the amount you hope for. If the packed lunches save fifty dollars a week, move forty. The plan should survive an ordinary week with no heroics in it.
This is Section 8 of Setright's principles — the habits that last — and it is the same machinery we use for long-term money. A goal three years out lives in savings, where it cannot fall in value before you need it. Money you will not touch for decades goes to work in investments instead, where compounding, the quiet process of your earnings making their own earnings, has time to do the heavy lifting.
What not to cut
Do not trim the things that keep you steady: the emergency money you would need if the car died tomorrow, any match your employer puts into your retirement savings, or every last small pleasure in your week. A plan that leaves you miserable gets abandoned in a month, and an abandoned plan saves nothing.
The goal is not a smaller life. It is the same life, minus the leaks, pointed at something you will actually be glad you bought.